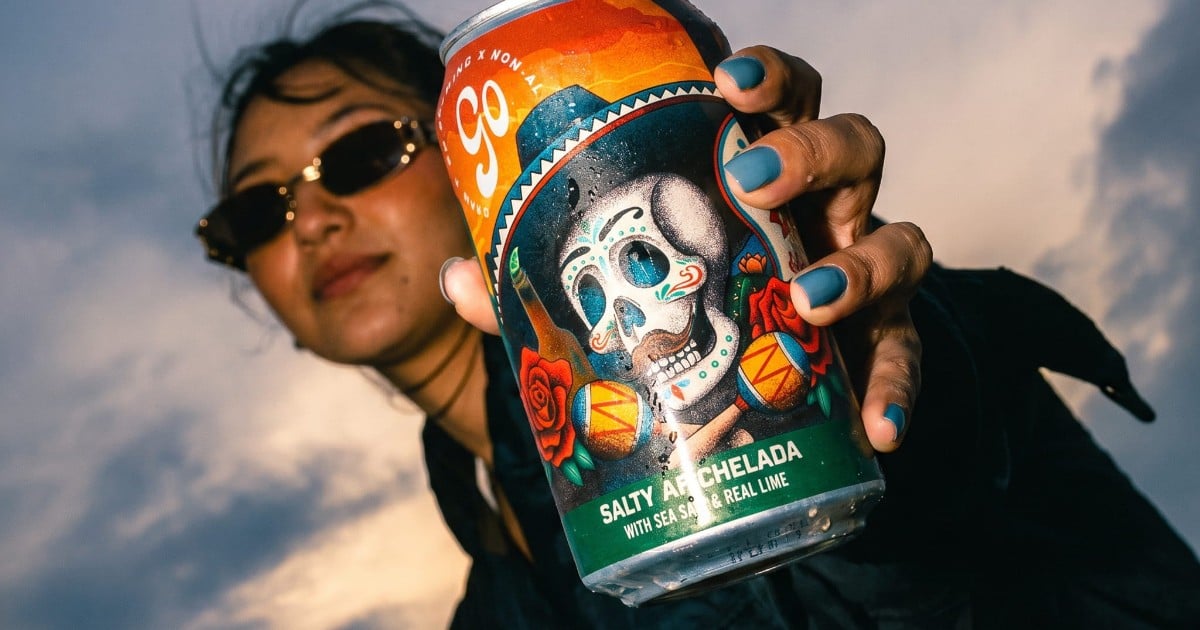
Go Brewing now opens its relationship with new visitors with a question. Last month, the brand added a three-question quiz to its signup flow. The first question asks what a visitor would want if a non-alc beer gave them “a little something extra.” Finishing the quiz adds 5% to the 20% cash back new customers already get on a first order.
In under two weeks, 2,419 people answered, and 1,524 of them wrote in their own words why they came. That’s a stage most brands never measure. Post-purchase surveys only reach buyers, and syndicated panels describe the category in aggregate, after the fact.
In this interview, founder and CEO Joe Chura shares what the quiz has shown, what Go Brewing has changed because of it, and where first-party data stops being useful.
Dry Atlas: More than half of quiz-takers had never heard of Go Brewing, even with thousands of doors behind you. Did that change anything about your approach?
Joe Chura: It didn’t surprise us, but it changed how we treat new visitors. Of the 2,419 people who’ve taken our signup quiz since September 18, 54% had never heard of Go Brewing. That tracks with our footprint. We’ve only been on shelves in a real way since late 2024, and we’re now past 9,000 doors. Our ACV is 9.8%; Athletic’s is 61.5%. Even so, our grocery sales are up 65% on last year. Awareness follows distribution. People find us on a shelf, then come online and stay.
So we assume every visitor is meeting us for the first time. Tell our quiz you just want beer that tastes like beer, and the homepage leads with our most beer-forward styles. We segment offers by what people tell us, and our in-house texting engine uses AI to follow up with an offer that fits.
DA: What personas did the open-text answers turn into, and which group didn’t you know existed?
JC: We landed on five: the committed abstainer, the mindful moderator, the gluten-free drinker who still loves beer, the curious light buyer, and the performance athlete. The moderator is the biggest. 62% of buyers who told us about their drinking are cutting back, not quitting.
The new quiz catches people before their first purchase, a stage we’d never measured. Most of the 1,524 write-ins confirmed what we knew: variety and new flavors (26% of the write-ins we could sort), tastes like real beer (17%), cutting back (11%), and gluten-free (4%). The surprise was a group I’d call pumpkin-first newcomers. 13% of write-ins mentioned pumpkin, and two-thirds of those people had never heard of Go. Some of that is timing, since the quiz launched with our pumpkin release, but it shows what’s pulling new people in right now. We also heard from parents drinking less because of their kids, a group we’ve made less content for.
DA: Where did the answers contradict what you assumed when you built the range? Has any of it changed a product, packaging, or pricing call?
JC: It mostly backed up the range we built. More than a third of the 2,360 people who answered said “just beer, please,” which matches three years of post-purchase data: taste comes first. Energy came in higher than we expected from a beer audience, right as energy drink brands start moving into the category.
Packaging is the clearest example of a call that changed. When we designed our cartons, we asked customers what they look for on a shelf once they’ve picked a style. Here’s what 919 of them told us:
| After finding a style, what matters most? | Share |
|---|---|
| A deeper look at the flavor profile | 50% |
| Nutrition labeling (gluten-free, calories, carbs) | 21% |
| Reviews, awards, and testimonials | 16% |
| Brand recognition | 6% |
| Alcohol content | 5% |
That’s what went on the carton, including real customer testimonials, which we hadn’t seen anyone else in the category do. Variety hasn’t changed either. It’s been the second most common reason people buy from us every half-year since 2024, so we built the business to deliver it. We can take a beer from idea to selling online in 21 days, fast enough to get a beer out while a format is still trending.
DA: You chose 20% cash back over a 15% discount, and 5% more for the text box. What does a completed non-buyer profile cost you, and what is it worth?
JC: Cash back costs less than a discount, and it only rewards buyers. It pays out 30 days after an order, once the return window closes, and only if the customer claims it. So a non-buyer’s completed profile costs nothing in incentive. More than 1,000 people finished the quiz between September 18 and 29 without ordering. Our real cost is the traffic, which we’d pay for anyway.
What we get back is 1,500 people telling us in their own words who they are and why they came. We’d otherwise pay a research firm for that. It’s too early to say whether quiz-takers are worth more over time.
DA: This is DTC-only intelligence. How much transfers to Whole Foods or Total Wine, and how do you correct for the bias?
JC: Most of it transfers, since it’s largely the same customers. The difference is how they shop. In a store, people choose by the carton on a crowded shelf. Online, they find us through social or search. 52% of online buyers on our older survey had never bought Go in a store, but 69% of them said it was because we weren’t available there. Only 8% said they’d rather buy online.
The channels feed each other. Customers who first found Go in a store, bar, or brewery spent about $240 with us online in their first year, versus about $141 for our average online customer.
Where we do correct for bias is sales mix. Retail decisions run on distributor depletion data, store by store. The site tells us what retail data can’t: why someone buys, what they want next, and which store they wish carried us.
DA: Athletic has far more first-party data than you, and the majors have extensive panel data. Where does a quiz-derived persona set beat that, and where doesn’t it?
JC: I’m sure Athletic has more data. They had a five-year-plus head start. But more data isn’t the game. The right question is. You only need a couple thousand responses to reach 95% confidence on most questions. Past that, more data doesn’t change what we’d do, so we retire the question and move on.
Where we beat panel data is speed and depth. Panels tell you what happened, months later, averaged across people who aren’t your customers. We’re looking for the smaller groups, like the pumpkin-first newcomer or the parent cutting back. The biggest payoff is new products. If you only follow panel data, you’re following trends someone else already started.
Where it falls short is scale and representativeness. It reflects our customers and visitors, skewed toward people who found us online, not the whole category. We don’t use it to size markets or plan distribution. We use it to decide what to say, who to say it to, and what to brew next.
This interview has been edited for length and clarity.